Insights & Opinions
Building Interest-Free Finance from Scratch: A Founder's Top of Mind for 2027
Mon, 16 Nov 2026
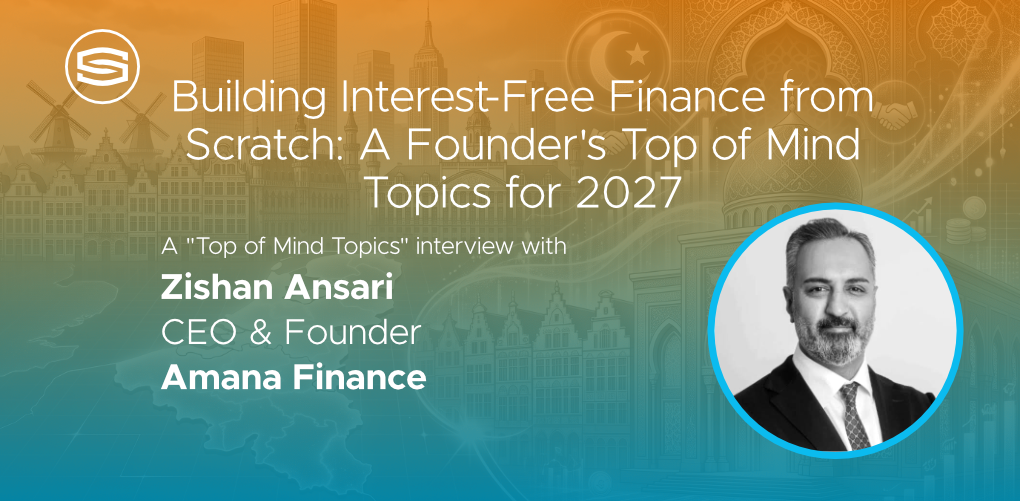
Most of the guests in our top-of-mind series will be looking at 2027 from inside an established institution, with a balance sheet, a brand and decades of customer relationships and regulation behind them. Zishan Ansari, CEO and founder of Amana Finance, is looking at it from the other end of the telescope. Amana plans to offer Sharia-compliant financial services, starting with a soft launch in Belgium in 2027.
So, when I asked for his top three top-of-mind topics, counted down from number three to number one in our usual "what, so what, now what" fashion, his answers were understandably those of a founder rather than an established banker. They are his personal priorities, not a manifesto for every Benelux banker, yet I think that is exactly what makes them interesting.
Watching someone build a financial service from nothing, for a community the industry has largely overlooked, holds up a revealing mirror to the rest of us.
How can we increase inclusion for a growing Muslim population in Europe?
Zishan's starting point is a gap between belief and the financial system. Europe is home to roughly 30 million Muslims, a population that is growing across the continent. Demand for Sharia-compliant products has been building for two decades, and yet, in his opinion, nobody has really stepped up to meet it.
This is not a story about the unbanked. As Zishan explained, everybody is banked locally, because everybody needs to transact locally. The issue is what happens beyond the basic current account. Many Muslim customers use only the bare minimum, daily banking, and steer clear of financing, investment and pension products because none of them are certified as compliant.
I will admit to some naivety here, because I had not even considered pensions! In Belgium, most pension savings products are largely invested in interest-bearing bonds. Opting out means missing a product that is not only valuable for retirement, but tax-deductible too. Multiply that by every salaried person in the community and you begin to see the scale of the missed opportunity.
The consequences run deeper than product take-up. Zishan described families held back from buying a home, which shapes the neighbourhood they live in, the schools their children attend and, sadly, the discrimination some face as tenants. He also described entrepreneurs who want to run their businesses in line with their beliefs, but cannot access the financing to compete on a level playing field.
When asked why the incumbents haven’t filled the gap, Zishan said that banks are aware of the issue, but face two legitimate questions: how credible is a Sharia-compliant product from an institution built on interest, and would launching one unsettle parts of an existing customer base? His response is to offer partnership rather than competition. Amana does not see itself as a rival to incumbent banks, and he is open to working with them.
There is also the matter of plumbing. Zishan pointed to the UK as Europe's most mature market, with compliant products for years, supported by a government willing to adapt the rules. A compliant home purchase, for example, requires the provider to own the property and sell it on, which in most Benelux countries would trigger property transfer taxes twice. The UK addressed that with a dedicated structure. Belgium has not yet done so, which is why Amana is exploring solutions, with its advisers, at the narrow intersection of three rulebooks: the financial regulator, property taxation and Islamic finance.
I reflected that this is structural work, not something you can simply bolt onto an existing product portfolio afterwards.
How can we build a community and establish trust?
If his number three top-of-mind topic for 2027 is the opportunity, his number two is the hardest part of seizing it. Today the community Amana wants to serve is scattered across incumbents and digital banks. Bringing it together means persuading people to hand their money to an institution they have never heard of.
Zishan put it well: the three things people are most protective of are their health, their money and their religion. Amana is asking for trust on two of the three at once. A Sharia certificate alone will not do it. He expects it to take time, the visible support of respected community leaders, and a steady roadmap of products that solve real pain points. He was candid that this will not be a smooth exercise.
I turned my usual closing question on its head and instead of asking what question he would put to a bank CEO, I asked what question from his own board would make him squirm. His answer revealed how much of trust comes down to clarity about roles.
The obvious question, he said, is how anyone can know a product is genuinely Sharia-compliant when this has barely been done in these markets before. His answer is unequivocal: Amana cannot self-certify and has no wish to. He drew a parallel with halal food, which has been sold in Belgian supermarkets for years. Shoppers accept the label because it rests on an independent chain of auditors, not on the word of the retailer.
Amana is replicating that model with an independent Sharia board whose role is to audit its financial transactions. The scholars follow the standards of AAOIFI, the Bahrain-based body that most of the Islamic finance world looks to, which gives the certification a global consensus. Their names, credentials, affiliations and certification process will be public. Certification is not a one-off either: products evolve, so the audits will be ongoing.
Zishan was equally firm about his own position. As founder and CEO, he has no religious authority whatsoever, and he wants both the community and the wider public to understand that. Amana is a business that saw a problem and is assembling the right partners to solve it. Just as a supermarket can sell a halal ready meal in one aisle and a bottle of wine in another, the presence of a compliant product does not make an institution a religious body.
I found this a valuable lesson for any bank, not just a challenger. Trust is rarely built by claiming virtue; it is built by being transparent about who decides what, who is accountable, and who checks the work.
Getting started
After all the talk of demographics, tax structures and Sharia boards, Zishan's number one priority was simple: get started. Amana aims to begin with a soft launch in Belgium in 2027, and everything else depends on getting the ball rolling.
I have a lot of sympathy for this. Anyone who has worked in innovation knows the trap of perfecting a proposition in the meeting room while the market moves on. Trust cannot be built in theory; it has to be earned one customer at a time, and that only starts once the doors are open.
Zishan sees two parallel tracks from there. The first is to grow the community and lay the foundations of trust, which in turn unlocks the more complex products the market needs. The second is to keep adding products to the ecosystem. He gave investments as an example. Many business owners he has spoken to have built up capital but are reluctant to put it into the stock market, because they cannot be sure the investments are compliant. In the meantime, inflation quietly erodes their savings, which helps neither them nor the local economy.
This led him to the point he clearly cares about most. He knows that inclusion of this kind may become a political debate, with different parties framing it in different ways. Amana wants no part of that. Its stance is neutral and pragmatic: give people financial tools that fit their beliefs, and they gain more financial power, more spending power and a greater stake in the economy around them, which benefits everyone.
The offer is not exclusive. Zishan compared it to the organic aisle in a supermarket: organic products are made to a particular set of standards, but nobody checks your credentials at the checkout. Anyone who likes what Amana offers will be welcome to use it.
For incumbents, I think there are two key takeaways. First, a sizeable and growing group of customers is using only a fraction of what banks offer, not through lack of need but through lack of suitable products. Second, the founders addressing that gap are not looking for a fight; they are looking for partners.
If you would like to hear more, Zishan will be in conversation with Rik in a fireside chat: “Finance Without Interest: Serving Europe’s Muslims”, at The Banking Scene Art Night on December 07 in Brussels.
We look forward to seeing many of you there and to watching how Amana's first year unfolds in 2027.
The Banking Scene: Director's Cut
If you prefer to sit back and relax with your favourite beverage, you can watch or listen to the full interview below or catch it on your favourite podcast channel here.